Category: Investing Basics

Beginner investing guides covering compounding, risk, time horizon, diversification, asset allocation, and investment basics.

  • Compound Interest Basics: How Compounding Grows Money Over Time

    Compound Interest Basics: How Compounding Grows Money Over Time

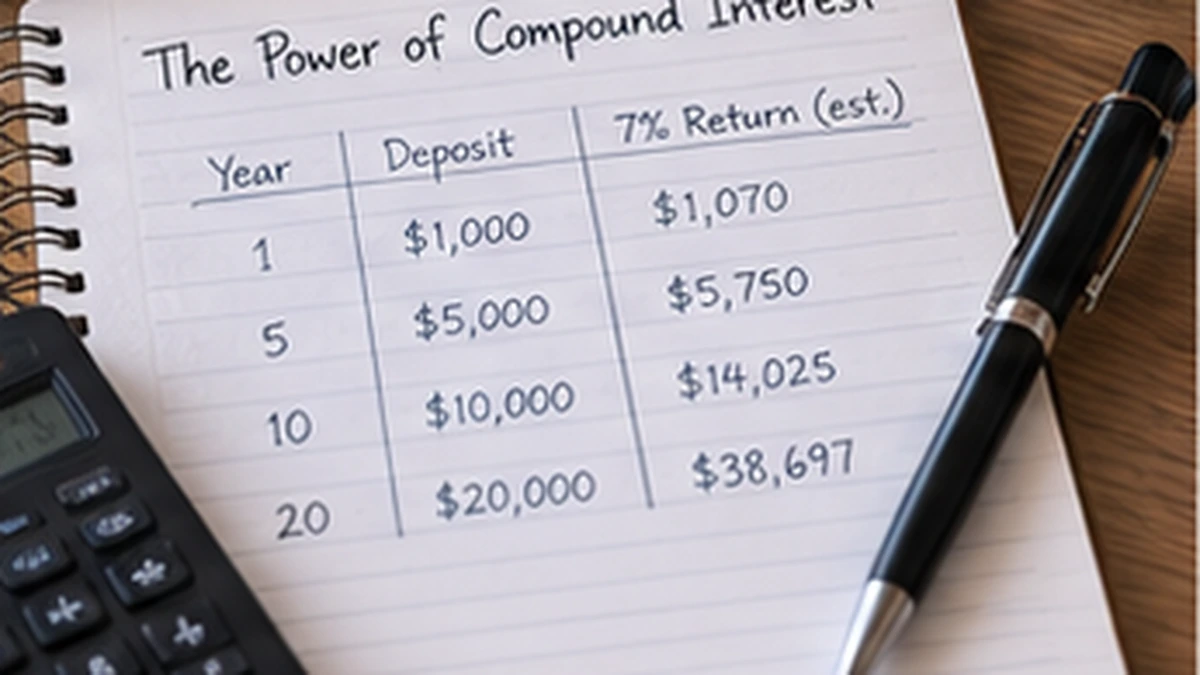
    Compound interest basics Compounding describes growth that builds on previous growth. Investor.gov defines compound interest as interest paid on principal and accumulated interest, which means time can become an important part of the result when money remains saved or invested.

    This guide explains compound interest basics for general financial education. It does not provide individualized investment, tax, legal, credit, or banking advice. Some authoritative sources are U.S.-focused, so readers elsewhere should verify local rules and product terms with the appropriate authority.

    Why compound interest basics matters

    Compounding works best as a planning concept, not a prediction. Use several rates and contribution levels instead of one optimistic scenario. Seeing a range of outcomes helps keep the plan realistic and shows which variable—time, contribution, fee, or return—has the biggest effect.

    Compound interest earns on earlier interest

    When interest is added to a balance, future interest can be calculated on both the original principal and the interest already credited.

    For compound interest basics, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 1: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    Time increases the number of compounding periods

    The longer money remains in an interest-bearing or growth-producing environment, the more opportunities previous earnings have to contribute to future growth.

    For compound interest basics, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 2: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    The rate changes the speed of growth

    A higher positive rate increases hypothetical growth, but higher expected investment returns can also come with higher risk and no guarantee.

    For compound interest basics, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 3: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    Regular contributions add new principal

    Adding money consistently creates more principal that can participate in future compounding.

    For compound interest basics, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 4: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    Fees reduce the balance left to grow

    Account fees, fund expenses, advisory costs, and other charges reduce the amount remaining to earn future returns.

    For compound interest basics, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 5: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    Compounding can also increase debt

    When unpaid interest is added to a debt balance, future interest can be charged on a larger amount depending on the product rules.

    For compound interest basics, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 6: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    Small differences become larger over long periods

    A modest difference in contribution, return, or fee can compound into a much larger difference after many years.

    For compound interest basics, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 7: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    Hypothetical returns are not promises

    Investment examples often assume a steady rate for illustration, while real market returns fluctuate and may be negative during some periods.

    For compound interest basics, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 8: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    Calculators are scenario tools

    Investor.gov provides calculators that show how assumptions about time, rate, and contributions affect hypothetical results.

    For compound interest basics, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 9: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    Connect compounding to a goal

    The concept becomes useful when it is linked to a specific time horizon such as retirement, education, a home purchase, or another long-term objective.

    For compound interest basics, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 10: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    A realistic example of compound interest basics

    A person wants to improve this part of their finances and initially focuses on one attractive number, such as a high rate, low fee, strong score, or recent return. After reviewing the full account terms, budget, risk, time horizon, and goal, the person chooses a plan that is easier to maintain. The example shows why compound interest basics should be connected to the whole financial picture rather than one headline figure.

    Connect this guide to the rest of the finance site

    Read investing basics for beginners for one related finance topic, and use retirement saving basics when the second guide helps you understand saving, credit, investing, retirement, or financial safety.

    These internal links connect the first Finance batch so readers can move between budgeting, banking, credit, investing, retirement, and fraud protection without repeating the same article.

    A seven-day review plan for compound interest basics

    Day 1: define the goal. Day 2: collect the relevant account, statement, report, or budget data. Day 3: compare the information with the authoritative source below. Day 4: identify costs, risks, and missing information. Day 5: make one small adjustment. Day 6: verify that the change worked as intended. Day 7: record the next step and a date to review the result again. Finance review note 6 for compound interest basics.

    The seven-day structure is only a framework. A credit-report correction or account transfer can require more time, while a simple budget or savings update may take less than an hour.

    Practical checklist

    • Purpose of compound interest basics identified
    • Current financial information collected
    • Costs, fees, or risks reviewed
    • Authoritative source checked
    • Assumptions separated from facts
    • Privacy and security considered
    • One practical next step selected
    • Review date scheduled

    Use the checklist to find the weakest part of your understanding of compound interest basics. One overlooked fee, report error, concentration risk, or security problem can matter more than several details you already understand.

    Frequently Asked Questions

    Is there one financial strategy that works for everyone?

    No. Income, expenses, goals, time horizon, taxes, debt, risk tolerance, and local rules differ. General frameworks should be adapted to the person’s actual situation.

    Should short-term savings and long-term investments be handled the same way?

    Usually not. Money needed soon generally needs more stability and access, while long-term investing can accept more market fluctuation depending on risk tolerance and the goal.

    Can one financial number tell me whether a decision is good?

    No. A rate, score, return, fee, or balance is only part of the picture. Review the product terms, cash-flow effect, risk, and goal together.

    Where should I verify financial information?

    Use the bank, regulator, tax authority, securities regulator, credit-reporting company, or other official source with authority over the product or issue in your jurisdiction.

    Practical review 1 for compound interest basics

    Take one real account, statement, report, or savings goal and explain it in plain language. Identify the amount involved, the cost or risk, what can change, and what action would improve the situation. If any part depends on a rule or product term you cannot verify, check it before acting. Finance review note 24 for compound interest basics.

    Then compare the current approach with one realistic alternative. The goal is not to find a perfect financial answer; it is to understand the trade-off well enough to choose the next step deliberately and to know what evidence would make you change that decision later. Finance review note 24 for compound interest basics.

    Practical review 2 for compound interest basics

    Take one real account, statement, report, or savings goal and explain it in plain language. Identify the amount involved, the cost or risk, what can change, and what action would improve the situation. If any part depends on a rule or product term you cannot verify, check it before acting. Finance review note 25 for compound interest basics.

    Then compare the current approach with one realistic alternative. The goal is not to find a perfect financial answer; it is to understand the trade-off well enough to choose the next step deliberately and to know what evidence would make you change that decision later. Finance review note 25 for compound interest basics.

    Practical review 3 for compound interest basics

    Take one real account, statement, report, or savings goal and explain it in plain language. Identify the amount involved, the cost or risk, what can change, and what action would improve the situation. If any part depends on a rule or product term you cannot verify, check it before acting. Finance review note 26 for compound interest basics.

    Then compare the current approach with one realistic alternative. The goal is not to find a perfect financial answer; it is to understand the trade-off well enough to choose the next step deliberately and to know what evidence would make you change that decision later. Finance review note 26 for compound interest basics.

    Practical review 4 for compound interest basics

    Take one real account, statement, report, or savings goal and explain it in plain language. Identify the amount involved, the cost or risk, what can change, and what action would improve the situation. If any part depends on a rule or product term you cannot verify, check it before acting. Finance review note 27 for compound interest basics.

    Then compare the current approach with one realistic alternative. The goal is not to find a perfect financial answer; it is to understand the trade-off well enough to choose the next step deliberately and to know what evidence would make you change that decision later. Finance review note 27 for compound interest basics.

    Practical review 5 for compound interest basics

    Take one real account, statement, report, or savings goal and explain it in plain language. Identify the amount involved, the cost or risk, what can change, and what action would improve the situation. If any part depends on a rule or product term you cannot verify, check it before acting. Finance review note 28 for compound interest basics.

    Then compare the current approach with one realistic alternative. The goal is not to find a perfect financial answer; it is to understand the trade-off well enough to choose the next step deliberately and to know what evidence would make you change that decision later. Finance review note 28 for compound interest basics.

    Authoritative resource to review

    For an authoritative reference related to this topic, review Investor.gov – What Is Compound Interest?. Use the source for the core principle, then verify the exact account terms, local rules, and personal circumstances before acting.

    Final perspective

    Compound interest basics becomes easier when the process is simple enough to repeat. Use real numbers, keep records, understand risk, protect accounts, and review the plan periodically instead of relying on one-time decisions or financial promises.
  • Investing Basics for Beginners: Risk, Time Horizon and Goals

    Investing Basics for Beginners: Risk, Time Horizon and Goals

    Investing basics for beginners Investing is the process of putting money into assets with the expectation of future return, but returns are uncertain and losses are possible. A beginner plan should therefore start with goals, time horizon, emergency savings, and risk tolerance before choosing specific investments.

    This guide explains investing basics for beginners for general financial education. It does not provide individualized investment, tax, legal, credit, or banking advice. Some authoritative sources are U.S.-focused, so readers elsewhere should verify local rules and product terms with the appropriate authority.

    Why investing basics for beginners matters

    A beginner investment decision should be explainable in one paragraph: the goal, time horizon, amount invested, risk accepted, fees paid, and reason the investment belongs in the portfolio. If that explanation is impossible, more research is needed before purchase.

    Start with the financial goal

    Investor.gov recommends defining goals and creating a plan before selecting investments.

    For investing basics for beginners, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 1: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    Separate short-term savings from investing

    Emergency funds and money needed soon generally require more stability and access than long-term investment money.

    For investing basics for beginners, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 2: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    Understand that all investments involve risk

    Stocks, bonds, funds, real estate, and other assets can lose value. There is no guaranteed market return.

    For investing basics for beginners, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 3: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    Match risk to time horizon

    A long time horizon can provide more time to recover from market fluctuations than a short-term goal.

    For investing basics for beginners, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 4: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    Consider personal risk tolerance

    The amount of volatility one investor can tolerate financially or emotionally may be very different from another investor.

    For investing basics for beginners, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 5: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    Understand the product before buying

    Know what you own, how it may generate return, which risks can create losses, and what restrictions apply.

    For investing basics for beginners, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 6: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    Review fees

    Expense ratios, advisory fees, trading charges, and account fees can reduce long-term results.

    For investing basics for beginners, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 7: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    Diversify rather than concentrating blindly

    Spreading exposure can reduce dependence on one company, sector, or asset type.

    For investing basics for beginners, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 8: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    Use regular contributions when they fit the plan

    Automated or scheduled investing can support discipline without requiring repeated timing decisions.

    For investing basics for beginners, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 9: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    Review the plan without chasing every market move

    A long-term strategy still needs review, but constant reactions to fear or excitement can undermine the original goal.

    For investing basics for beginners, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 10: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    A realistic example of investing basics for beginners

    A person wants to improve this part of their finances and initially focuses on one attractive number, such as a high rate, low fee, strong score, or recent return. After reviewing the full account terms, budget, risk, time horizon, and goal, the person chooses a plan that is easier to maintain. The example shows why investing basics for beginners should be connected to the whole financial picture rather than one headline figure.

    Connect this guide to the rest of the finance site

    Read compound interest basics for one related finance topic, and use diversification and asset allocation when the second guide helps you understand saving, credit, investing, retirement, or financial safety.

    These internal links connect the first Finance batch so readers can move between budgeting, banking, credit, investing, retirement, and fraud protection without repeating the same article.

    A seven-day review plan for investing basics for beginners

    Day 1: define the goal. Day 2: collect the relevant account, statement, report, or budget data. Day 3: compare the information with the authoritative source below. Day 4: identify costs, risks, and missing information. Day 5: make one small adjustment. Day 6: verify that the change worked as intended. Day 7: record the next step and a date to review the result again. Finance review note 7 for investing basics for beginners.

    The seven-day structure is only a framework. A credit-report correction or account transfer can require more time, while a simple budget or savings update may take less than an hour.

    Practical checklist

    • Purpose of investing basics for beginners identified
    • Current financial information collected
    • Costs, fees, or risks reviewed
    • Authoritative source checked
    • Assumptions separated from facts
    • Privacy and security considered
    • One practical next step selected
    • Review date scheduled

    Use the checklist to find the weakest part of your understanding of investing basics for beginners. One overlooked fee, report error, concentration risk, or security problem can matter more than several details you already understand.

    Frequently Asked Questions

    Is there one financial strategy that works for everyone?

    No. Income, expenses, goals, time horizon, taxes, debt, risk tolerance, and local rules differ. General frameworks should be adapted to the person’s actual situation.

    Should short-term savings and long-term investments be handled the same way?

    Usually not. Money needed soon generally needs more stability and access, while long-term investing can accept more market fluctuation depending on risk tolerance and the goal.

    Can one financial number tell me whether a decision is good?

    No. A rate, score, return, fee, or balance is only part of the picture. Review the product terms, cash-flow effect, risk, and goal together.

    Where should I verify financial information?

    Use the bank, regulator, tax authority, securities regulator, credit-reporting company, or other official source with authority over the product or issue in your jurisdiction.

    Practical review 1 for investing basics for beginners

    Take one real account, statement, report, or savings goal and explain it in plain language. Identify the amount involved, the cost or risk, what can change, and what action would improve the situation. If any part depends on a rule or product term you cannot verify, check it before acting. Finance review note 29 for investing basics for beginners.

    Then compare the current approach with one realistic alternative. The goal is not to find a perfect financial answer; it is to understand the trade-off well enough to choose the next step deliberately and to know what evidence would make you change that decision later. Finance review note 29 for investing basics for beginners.

    Practical review 2 for investing basics for beginners

    Take one real account, statement, report, or savings goal and explain it in plain language. Identify the amount involved, the cost or risk, what can change, and what action would improve the situation. If any part depends on a rule or product term you cannot verify, check it before acting. Finance review note 30 for investing basics for beginners.

    Then compare the current approach with one realistic alternative. The goal is not to find a perfect financial answer; it is to understand the trade-off well enough to choose the next step deliberately and to know what evidence would make you change that decision later. Finance review note 30 for investing basics for beginners.

    Practical review 3 for investing basics for beginners

    Take one real account, statement, report, or savings goal and explain it in plain language. Identify the amount involved, the cost or risk, what can change, and what action would improve the situation. If any part depends on a rule or product term you cannot verify, check it before acting. Finance review note 31 for investing basics for beginners.

    Then compare the current approach with one realistic alternative. The goal is not to find a perfect financial answer; it is to understand the trade-off well enough to choose the next step deliberately and to know what evidence would make you change that decision later. Finance review note 31 for investing basics for beginners.

    Practical review 4 for investing basics for beginners

    Take one real account, statement, report, or savings goal and explain it in plain language. Identify the amount involved, the cost or risk, what can change, and what action would improve the situation. If any part depends on a rule or product term you cannot verify, check it before acting. Finance review note 32 for investing basics for beginners.

    Then compare the current approach with one realistic alternative. The goal is not to find a perfect financial answer; it is to understand the trade-off well enough to choose the next step deliberately and to know what evidence would make you change that decision later. Finance review note 32 for investing basics for beginners.

    Practical review 5 for investing basics for beginners

    Take one real account, statement, report, or savings goal and explain it in plain language. Identify the amount involved, the cost or risk, what can change, and what action would improve the situation. If any part depends on a rule or product term you cannot verify, check it before acting. Finance review note 33 for investing basics for beginners.

    Then compare the current approach with one realistic alternative. The goal is not to find a perfect financial answer; it is to understand the trade-off well enough to choose the next step deliberately and to know what evidence would make you change that decision later. Finance review note 33 for investing basics for beginners.

    Authoritative resource to review

    For an authoritative reference related to this topic, review Investor.gov – Introduction to Investing. Use the source for the core principle, then verify the exact account terms, local rules, and personal circumstances before acting.

    Final perspective

    Investing basics for beginners becomes easier when the process is simple enough to repeat. Use real numbers, keep records, understand risk, protect accounts, and review the plan periodically instead of relying on one-time decisions or financial promises.

  • Diversification and Asset Allocation: How They Reduce Concentration Risk

    Diversification and Asset Allocation: How They Reduce Concentration Risk

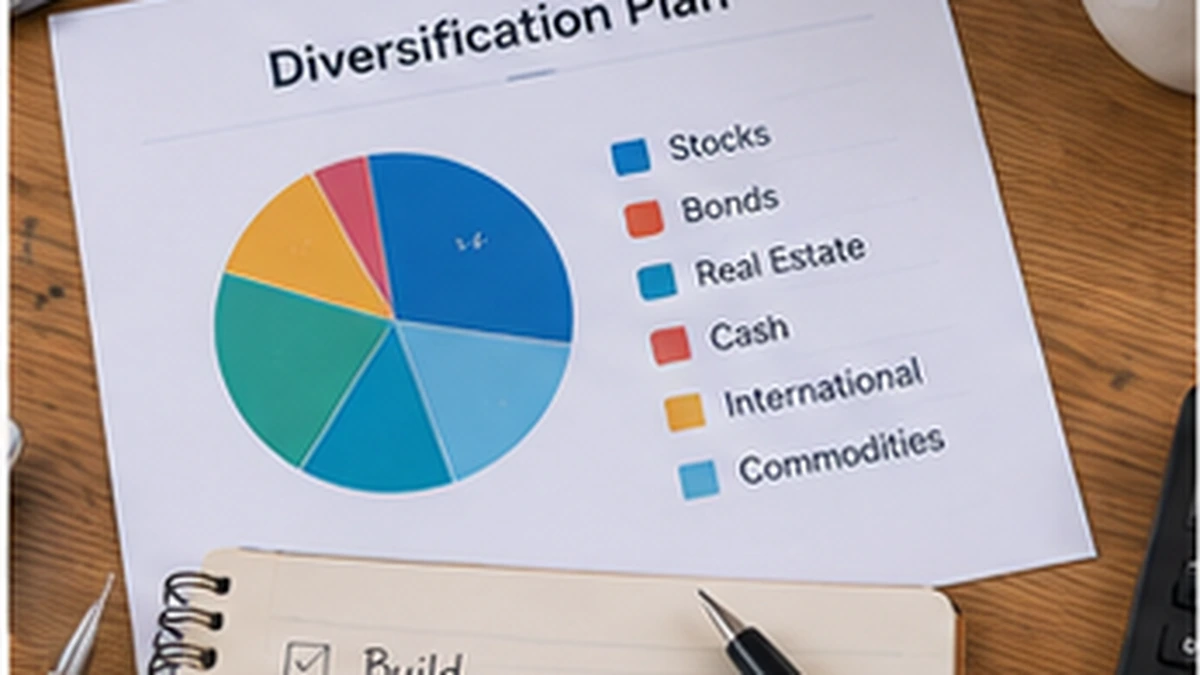
    Diversification and asset allocation Asset allocation and diversification are related risk-management ideas. Allocation decides how much of the portfolio sits in broad asset classes, while diversification spreads exposure so the portfolio does not depend too heavily on one company, sector, asset, or market outcome.

    This guide explains diversification and asset allocation for general financial education. It does not provide individualized investment, tax, legal, credit, or banking advice. Some authoritative sources are U.S.-focused, so readers elsewhere should verify local rules and product terms with the appropriate authority.

    Why diversification and asset allocation matters

    Diversification should be evaluated by exposure, not by the number of holdings. Ten funds that all own similar technology companies may be less diversified than a smaller set that truly spans different asset classes and market risks.

    Asset allocation divides money among broad asset classes

    Stocks, bonds, cash, and other asset categories behave differently, so the mix affects both expected return and volatility.

    For diversification and asset allocation, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 1: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    Diversification spreads exposure

    Investor.gov summarizes diversification as not putting all your eggs in one basket.

    For diversification and asset allocation, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 2: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    Time horizon affects allocation

    Investors with longer horizons may be able to tolerate more volatility than investors who need the money soon.

    For diversification and asset allocation, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 3: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    Risk tolerance also matters

    The appropriate mix depends on both willingness and financial ability to accept losses.

    For diversification and asset allocation, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 4: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    One stock is not diversified

    A portfolio concentrated in one company depends heavily on that company’s results and risks.

    For diversification and asset allocation, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 5: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    A thematic fund can still be concentrated

    A fund can hold many securities while remaining heavily exposed to one sector, country, or investment theme.

    For diversification and asset allocation, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 6: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    Diversification cannot prevent all losses

    Broad market declines can affect many holdings at the same time, so diversification reduces concentration risk rather than eliminating investment risk.

    For diversification and asset allocation, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 7: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    Cash can support short-term stability

    Cash can reduce volatility and support near-term needs, although too much cash can limit long-term growth potential.

    For diversification and asset allocation, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 8: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    Rebalancing restores the target mix

    Market movement can push the portfolio away from the intended allocation, so periodic rebalancing may be used to restore the chosen proportions.

    For diversification and asset allocation, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 9: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    Costs and taxes can affect rebalancing

    Buying and selling can create transaction costs or tax consequences depending on the account and jurisdiction.

    For diversification and asset allocation, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 10: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.

    A realistic example of diversification and asset allocation

    A person wants to improve this part of their finances and initially focuses on one attractive number, such as a high rate, low fee, strong score, or recent return. After reviewing the full account terms, budget, risk, time horizon, and goal, the person chooses a plan that is easier to maintain. The example shows why diversification and asset allocation should be connected to the whole financial picture rather than one headline figure.

    Connect this guide to the rest of the finance site

    Read investing basics for beginners for one related finance topic, and use retirement saving basics when the second guide helps you understand saving, credit, investing, retirement, or financial safety.

    These internal links connect the first Finance batch so readers can move between budgeting, banking, credit, investing, retirement, and fraud protection without repeating the same article.

    A seven-day review plan for diversification and asset allocation

    Day 1: define the goal. Day 2: collect the relevant account, statement, report, or budget data. Day 3: compare the information with the authoritative source below. Day 4: identify costs, risks, and missing information. Day 5: make one small adjustment. Day 6: verify that the change worked as intended. Day 7: record the next step and a date to review the result again. Finance review note 8 for diversification and asset allocation.

    The seven-day structure is only a framework. A credit-report correction or account transfer can require more time, while a simple budget or savings update may take less than an hour.

    Practical checklist

    • Purpose of diversification and asset allocation identified
    • Current financial information collected
    • Costs, fees, or risks reviewed
    • Authoritative source checked
    • Assumptions separated from facts
    • Privacy and security considered
    • One practical next step selected
    • Review date scheduled

    Use the checklist to find the weakest part of your understanding of diversification and asset allocation. One overlooked fee, report error, concentration risk, or security problem can matter more than several details you already understand.

    Frequently Asked Questions

    Is there one financial strategy that works for everyone?

    No. Income, expenses, goals, time horizon, taxes, debt, risk tolerance, and local rules differ. General frameworks should be adapted to the person’s actual situation.

    Should short-term savings and long-term investments be handled the same way?

    Usually not. Money needed soon generally needs more stability and access, while long-term investing can accept more market fluctuation depending on risk tolerance and the goal.

    Can one financial number tell me whether a decision is good?

    No. A rate, score, return, fee, or balance is only part of the picture. Review the product terms, cash-flow effect, risk, and goal together.

    Where should I verify financial information?

    Use the bank, regulator, tax authority, securities regulator, credit-reporting company, or other official source with authority over the product or issue in your jurisdiction.

    Practical review 1 for diversification and asset allocation

    Take one real account, statement, report, or savings goal and explain it in plain language. Identify the amount involved, the cost or risk, what can change, and what action would improve the situation. If any part depends on a rule or product term you cannot verify, check it before acting. Finance review note 34 for diversification and asset allocation.

    Then compare the current approach with one realistic alternative. The goal is not to find a perfect financial answer; it is to understand the trade-off well enough to choose the next step deliberately and to know what evidence would make you change that decision later. Finance review note 34 for diversification and asset allocation.

    Practical review 2 for diversification and asset allocation

    Take one real account, statement, report, or savings goal and explain it in plain language. Identify the amount involved, the cost or risk, what can change, and what action would improve the situation. If any part depends on a rule or product term you cannot verify, check it before acting. Finance review note 35 for diversification and asset allocation.

    Then compare the current approach with one realistic alternative. The goal is not to find a perfect financial answer; it is to understand the trade-off well enough to choose the next step deliberately and to know what evidence would make you change that decision later. Finance review note 35 for diversification and asset allocation.

    Practical review 3 for diversification and asset allocation

    Take one real account, statement, report, or savings goal and explain it in plain language. Identify the amount involved, the cost or risk, what can change, and what action would improve the situation. If any part depends on a rule or product term you cannot verify, check it before acting. Finance review note 36 for diversification and asset allocation.

    Then compare the current approach with one realistic alternative. The goal is not to find a perfect financial answer; it is to understand the trade-off well enough to choose the next step deliberately and to know what evidence would make you change that decision later. Finance review note 36 for diversification and asset allocation.

    Practical review 4 for diversification and asset allocation

    Take one real account, statement, report, or savings goal and explain it in plain language. Identify the amount involved, the cost or risk, what can change, and what action would improve the situation. If any part depends on a rule or product term you cannot verify, check it before acting. Finance review note 37 for diversification and asset allocation.

    Then compare the current approach with one realistic alternative. The goal is not to find a perfect financial answer; it is to understand the trade-off well enough to choose the next step deliberately and to know what evidence would make you change that decision later. Finance review note 37 for diversification and asset allocation.

    Practical review 5 for diversification and asset allocation

    Take one real account, statement, report, or savings goal and explain it in plain language. Identify the amount involved, the cost or risk, what can change, and what action would improve the situation. If any part depends on a rule or product term you cannot verify, check it before acting. Finance review note 38 for diversification and asset allocation.

    Then compare the current approach with one realistic alternative. The goal is not to find a perfect financial answer; it is to understand the trade-off well enough to choose the next step deliberately and to know what evidence would make you change that decision later. Finance review note 38 for diversification and asset allocation.

    Authoritative resource to review

    For an authoritative reference related to this topic, review Investor.gov – Asset Allocation and Diversification. Use the source for the core principle, then verify the exact account terms, local rules, and personal circumstances before acting.

    Final perspective

    Diversification and asset allocation becomes easier when the process is simple enough to repeat. Use real numbers, keep records, understand risk, protect accounts, and review the plan periodically instead of relying on one-time decisions or financial promises.