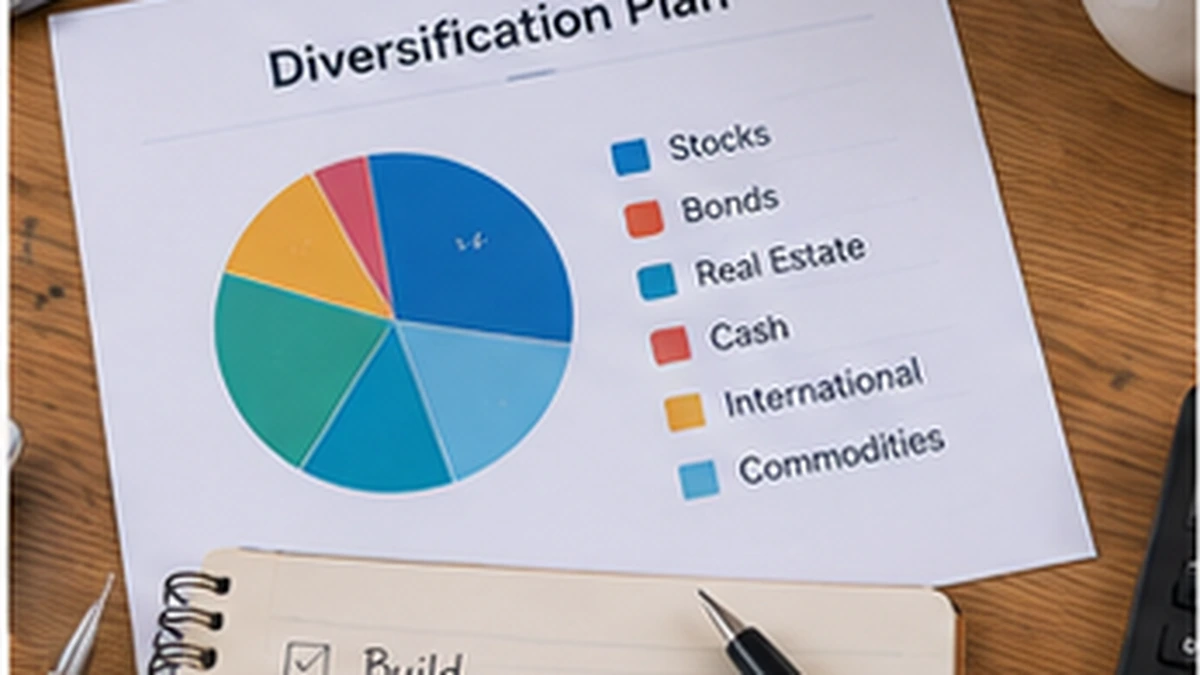
Diversification and asset allocation Asset allocation and diversification are related risk-management ideas. Allocation decides how much of the portfolio sits in broad asset classes, while diversification spreads exposure so the portfolio does not depend too heavily on one company, sector, asset, or market outcome.
This guide explains diversification and asset allocation for general financial education. It does not provide individualized investment, tax, legal, credit, or banking advice. Some authoritative sources are U.S.-focused, so readers elsewhere should verify local rules and product terms with the appropriate authority.
Why diversification and asset allocation matters
Diversification should be evaluated by exposure, not by the number of holdings. Ten funds that all own similar technology companies may be less diversified than a smaller set that truly spans different asset classes and market risks.
Asset allocation divides money among broad asset classes
Stocks, bonds, cash, and other asset categories behave differently, so the mix affects both expected return and volatility.
For diversification and asset allocation, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 1: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.
Diversification spreads exposure
Investor.gov summarizes diversification as not putting all your eggs in one basket.
For diversification and asset allocation, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 2: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.
Time horizon affects allocation
Investors with longer horizons may be able to tolerate more volatility than investors who need the money soon.
For diversification and asset allocation, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 3: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.
Risk tolerance also matters
The appropriate mix depends on both willingness and financial ability to accept losses.
For diversification and asset allocation, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 4: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.
One stock is not diversified
A portfolio concentrated in one company depends heavily on that company’s results and risks.
For diversification and asset allocation, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 5: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.
A thematic fund can still be concentrated
A fund can hold many securities while remaining heavily exposed to one sector, country, or investment theme.
For diversification and asset allocation, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 6: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.
Diversification cannot prevent all losses
Broad market declines can affect many holdings at the same time, so diversification reduces concentration risk rather than eliminating investment risk.
For diversification and asset allocation, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 7: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.
Cash can support short-term stability
Cash can reduce volatility and support near-term needs, although too much cash can limit long-term growth potential.
For diversification and asset allocation, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 8: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.
Rebalancing restores the target mix
Market movement can push the portfolio away from the intended allocation, so periodic rebalancing may be used to restore the chosen proportions.
For diversification and asset allocation, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 9: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.
Costs and taxes can affect rebalancing
Buying and selling can create transaction costs or tax consequences depending on the account and jurisdiction.
For diversification and asset allocation, connect this section to one real number, account, report item, contribution, or decision in your own finances. Review checkpoint 10: write the relevant amount, date, fee, balance, or goal so the idea can be tested rather than remaining theoretical.
A realistic example of diversification and asset allocation
A person wants to improve this part of their finances and initially focuses on one attractive number, such as a high rate, low fee, strong score, or recent return. After reviewing the full account terms, budget, risk, time horizon, and goal, the person chooses a plan that is easier to maintain. The example shows why diversification and asset allocation should be connected to the whole financial picture rather than one headline figure.
Connect this guide to the rest of the finance site
Read investing basics for beginners for one related finance topic, and use retirement saving basics when the second guide helps you understand saving, credit, investing, retirement, or financial safety.
These internal links connect the first Finance batch so readers can move between budgeting, banking, credit, investing, retirement, and fraud protection without repeating the same article.
A seven-day review plan for diversification and asset allocation
Day 1: define the goal. Day 2: collect the relevant account, statement, report, or budget data. Day 3: compare the information with the authoritative source below. Day 4: identify costs, risks, and missing information. Day 5: make one small adjustment. Day 6: verify that the change worked as intended. Day 7: record the next step and a date to review the result again. Finance review note 8 for diversification and asset allocation.
The seven-day structure is only a framework. A credit-report correction or account transfer can require more time, while a simple budget or savings update may take less than an hour.
Practical checklist
- Purpose of diversification and asset allocation identified
- Current financial information collected
- Costs, fees, or risks reviewed
- Authoritative source checked
- Assumptions separated from facts
- Privacy and security considered
- One practical next step selected
- Review date scheduled
Use the checklist to find the weakest part of your understanding of diversification and asset allocation. One overlooked fee, report error, concentration risk, or security problem can matter more than several details you already understand.
Frequently Asked Questions
Is there one financial strategy that works for everyone?
No. Income, expenses, goals, time horizon, taxes, debt, risk tolerance, and local rules differ. General frameworks should be adapted to the person’s actual situation.
Should short-term savings and long-term investments be handled the same way?
Usually not. Money needed soon generally needs more stability and access, while long-term investing can accept more market fluctuation depending on risk tolerance and the goal.
Can one financial number tell me whether a decision is good?
No. A rate, score, return, fee, or balance is only part of the picture. Review the product terms, cash-flow effect, risk, and goal together.
Where should I verify financial information?
Use the bank, regulator, tax authority, securities regulator, credit-reporting company, or other official source with authority over the product or issue in your jurisdiction.
Practical review 1 for diversification and asset allocation
Take one real account, statement, report, or savings goal and explain it in plain language. Identify the amount involved, the cost or risk, what can change, and what action would improve the situation. If any part depends on a rule or product term you cannot verify, check it before acting. Finance review note 34 for diversification and asset allocation.
Then compare the current approach with one realistic alternative. The goal is not to find a perfect financial answer; it is to understand the trade-off well enough to choose the next step deliberately and to know what evidence would make you change that decision later. Finance review note 34 for diversification and asset allocation.
Practical review 2 for diversification and asset allocation
Take one real account, statement, report, or savings goal and explain it in plain language. Identify the amount involved, the cost or risk, what can change, and what action would improve the situation. If any part depends on a rule or product term you cannot verify, check it before acting. Finance review note 35 for diversification and asset allocation.
Then compare the current approach with one realistic alternative. The goal is not to find a perfect financial answer; it is to understand the trade-off well enough to choose the next step deliberately and to know what evidence would make you change that decision later. Finance review note 35 for diversification and asset allocation.
Practical review 3 for diversification and asset allocation
Take one real account, statement, report, or savings goal and explain it in plain language. Identify the amount involved, the cost or risk, what can change, and what action would improve the situation. If any part depends on a rule or product term you cannot verify, check it before acting. Finance review note 36 for diversification and asset allocation.
Then compare the current approach with one realistic alternative. The goal is not to find a perfect financial answer; it is to understand the trade-off well enough to choose the next step deliberately and to know what evidence would make you change that decision later. Finance review note 36 for diversification and asset allocation.
Practical review 4 for diversification and asset allocation
Take one real account, statement, report, or savings goal and explain it in plain language. Identify the amount involved, the cost or risk, what can change, and what action would improve the situation. If any part depends on a rule or product term you cannot verify, check it before acting. Finance review note 37 for diversification and asset allocation.
Then compare the current approach with one realistic alternative. The goal is not to find a perfect financial answer; it is to understand the trade-off well enough to choose the next step deliberately and to know what evidence would make you change that decision later. Finance review note 37 for diversification and asset allocation.
Practical review 5 for diversification and asset allocation
Take one real account, statement, report, or savings goal and explain it in plain language. Identify the amount involved, the cost or risk, what can change, and what action would improve the situation. If any part depends on a rule or product term you cannot verify, check it before acting. Finance review note 38 for diversification and asset allocation.
Then compare the current approach with one realistic alternative. The goal is not to find a perfect financial answer; it is to understand the trade-off well enough to choose the next step deliberately and to know what evidence would make you change that decision later. Finance review note 38 for diversification and asset allocation.
Authoritative resource to review
For an authoritative reference related to this topic, review Investor.gov – Asset Allocation and Diversification. Use the source for the core principle, then verify the exact account terms, local rules, and personal circumstances before acting.
Final perspective
Diversification and asset allocation becomes easier when the process is simple enough to repeat. Use real numbers, keep records, understand risk, protect accounts, and review the plan periodically instead of relying on one-time decisions or financial promises.
Leave a Reply